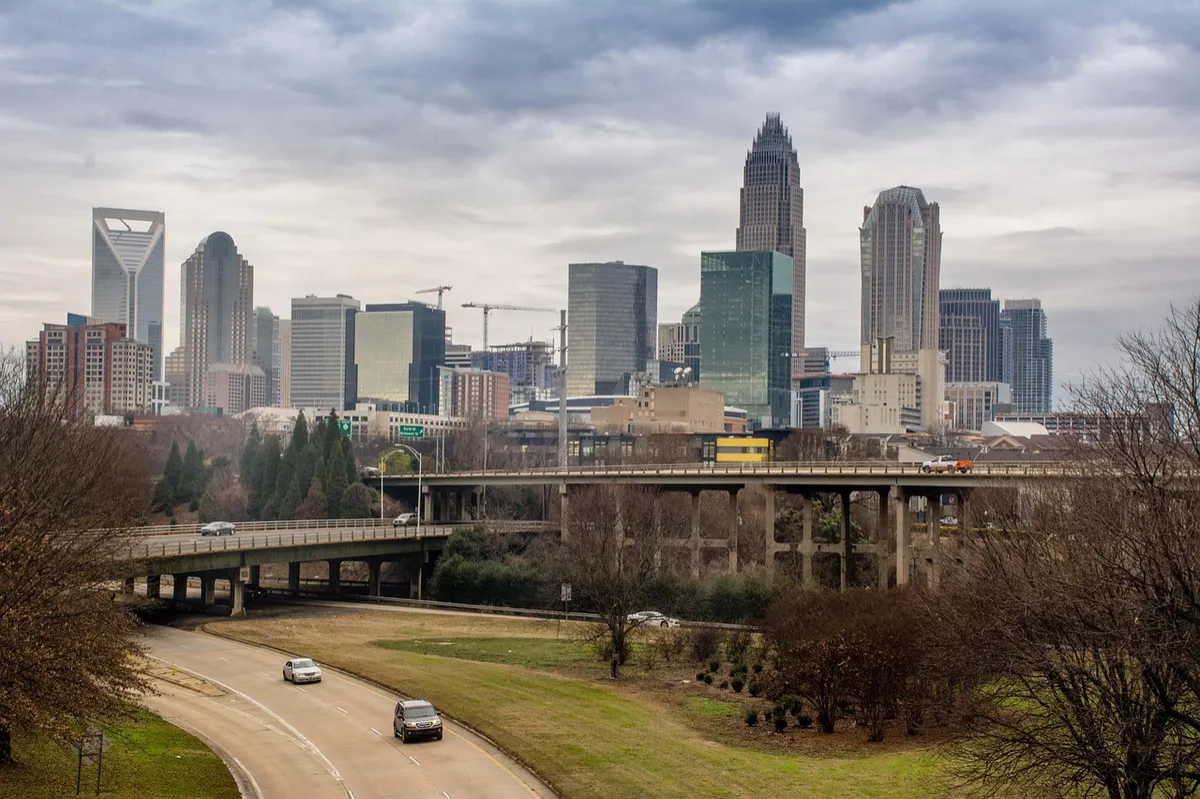
The Arguments Against Charlotte
By the Tide & Timber Investments team, a veteran-owned residential developer in Charlotte, North Carolina, and an affiliate of Tide & Timber Ventures, LLC. Last updated 21 October 2026.
Quick answer: The main risks to the Charlotte housing market are affordability (mortgage rates averaged 7.40% nationally as of the week of 15 October 2026, per Freddie Mac), rising insurance and property-tax costs, new supply competing for buyers, the region’s reliance on a few big industries such as finance, and slowing migration, which supplies most of North Carolina’s growth. None of these means Charlotte is a bad market. Each one means a deal has to work without assuming the boom continues.
Information current as of 21 October 2026, 9:54 PM ET. Rules, fees, maps and market figures change. Anything we could not confirm from an official source has been left out of this article. Check the linked official sources before relying on any detail.
We just looked at the case for Charlotte in Why Charlotte: The Growth Math. Now we argue the other side, because a good decision weighs both.
We’re a Charlotte developer. We build here, so you’d expect us to be bullish. That’s exactly why this article exists. The growth story is easy to find; the honest case against it is harder. If you can’t state the arguments against a market, you don’t understand the market yet.
Below are eight arguments, what to look at for each, and the question each one should make you ask about any deal.
1. Can buyers still afford Charlotte?
Part of Charlotte’s appeal has been its cost compared with the places people moved from. Years of price growth narrow that kind of gap, so check today’s prices against local incomes rather than relying on an old reputation.
The bigger squeeze is borrowing costs. Freddie Mac’s Primary Mortgage Market Survey put the national average 30-year fixed mortgage rate at 7.40% as of the week of 15 October 2026, up from 6.27% a year earlier.
Illustration only (our arithmetic, using a standard 30-year payment formula): on a $400,000 loan, that difference adds roughly $300 a month to principal and interest.
When payments rise faster than incomes, fewer households qualify, sales slow and sellers may have to cut prices or offer concessions.
Ask: At today’s rates, who can afford to buy or rent this property, and is that pool of buyers or renters large enough?
2. What if insurance keeps rising?
Homeowners insurance has become a real cost line in North Carolina. On 17 January 2025, the NC Department of Insurance announced a settlement with the NC Rate Bureau that set an average statewide base-rate increase of 7.5% from 1 June 2025, after the Rate Bureau had asked for an average of 42.2%. Check the Department of Insurance for current rates. Your own premium depends on location, the home and the insurer.
Being far from the coast doesn’t make a property risk-free. Inland areas still face wind, storm and flood risk, and insurers price that into their rates.
Ask: Does the deal use a current insurance quote, or last year’s number? What happens to the numbers if premiums rise again at renewal?
3. What about property taxes?
Counties periodically revalue property. When values jump, tax bills can rise even if the tax rate falls. Each county in the region sets its own schedule; check the county assessor for the next revaluation date.
Ask: Is the tax figure based on the current bill, and what happens if it rises after the next revaluation?
4. Is too much being built?
Growth attracts builders, of homes and of apartments. More supply is good for buyers and renters. For an investor, it can mean more competition, longer time on the market and less pricing power.
New homes from large builders can also come with incentives that small builders and individual sellers can’t always match.
You can check the supply side yourself. The Census Bureau’s Building Permits Survey shows how many new homes were authorised by metro area and county, and local listing reports show how many homes are for sale and how long they take to sell.
Ask: How many similar homes are for sale or under construction nearby? How long are they taking to sell?
5. Is Charlotte too dependent on banking?
Finance is one of Charlotte’s best-known industries. The Bureau of Labor Statistics “Economy at a Glance” page for the Charlotte-Concord-Gastonia metro shows the current number of jobs in financial activities alongside total employment; look at it and judge the share for yourself.
The risks are concentration risks:
- A downturn in finance (a banking crisis, a wave of mergers) could hit many local households at once.
- Automation and AI may change how many back-office and operations roles banks need.
- Remote and hybrid work let some employers hire elsewhere.
Other industries reduce this risk, but no regional economy is immune to a downturn in a major employer base.
Ask: Who are the likely buyers or tenants for this property, and how exposed are their jobs to one industry?
6. What if people stop moving here?
North Carolina’s growth is mostly migration, not births. That makes it sensitive to anything that changes migration. According to the NC Office of State Budget and Management (Demographic Outlook, 7 April 2026):
- The state’s population growth fell from about 180,000 in 2023–24 to about 146,000 in 2024–25.
- International migration to the state fell from 83,000 to 47,000 over the same period, and OSBM expects further declines because of federal policy changes.
- OSBM projects that North Carolina will have more deaths than births by 2033.
Charlotte still added more residents than any other US city between July 2024 and July 2025 (US Census Bureau, May 2026). But if domestic migration also cools, growth could slow faster than many pro formas assume. More detail in Why Charlotte: The Growth Math.
Ask: Does this deal still work if growth slows to half of today’s pace?
7. Can infrastructure keep up?
Fast growth strains roads, schools, water and sewer capacity. Commutes lengthen. Some lots face utility capacity limits or long waits for connections. Plans for new transit and road projects depend on funding and approvals that can change.
For investors, infrastructure shows up in two ways: delays and costs on individual projects, and quality-of-life pressures that can slow a region’s appeal over time.
Ask: Has the utility provider confirmed water and sewer capacity for this lot? (See The Charlotte Deal-Killer Field Guide (coming soon).)
8. What if the rules change?
The City of Charlotte’s Unified Development Ordinance (UDO) took effect on 1 June 2023. Rules like these get reviewed and amended. Towns and counties around Charlotte each have their own ordinances and fees, and those change too. A strategy built on today’s zoning can be undercut by tomorrow’s amendment.
Ask: Which rulebook applies to this lot, and is anything under review?
The risks at a glance
| Risk | What could happen | What to check |
|---|---|---|
| Affordability | Fewer qualified buyers, slower sales | Today’s mortgage rates and local incomes |
| Insurance | Higher carrying and ownership costs | A current quote, not an estimate |
| Property tax | Higher bills after revaluation | Current bill; next revaluation date |
| New supply | More competition, lower pricing power | Permits, active listings, nearby construction |
| Industry concentration | Many local jobs hit at once | Tenant or buyer profile; BLS industry data |
| Slowing migration | Lower demand than planned | Latest Census and OSBM figures |
| Infrastructure | Delays, connection costs | Utility confirmation |
| Rule changes | Fewer homes allowed, new fees | City or town planning updates |
So why invest here at all?
Because every market has a case against it. Charlotte’s risks are real, but so is its recent record: no US city added more residents between July 2024 and July 2025. The point isn’t to decide whether Charlotte is “good” or “bad”. It’s to make sure any deal you consider works under realistic, not optimistic, assumptions.
A useful habit: for every deal, write down the one risk on this list that would hurt it most, and ask the sponsor or seller how they’ve accounted for it. If they can’t answer, that’s your answer.
Keep reading: Don’t take our word for either side. You can check the market yourself, for free. Where to Find Charlotte Market Data for Free.
Frequently asked questions
Is the Charlotte housing market going to crash?
Nobody can predict that. The risks above (high mortgage rates, rising insurance, more supply and slowing migration) could cause prices to flatten or fall in some areas. Look at current local data, such as inventory and days on market, rather than headlines.
Is Charlotte overpriced?
It depends on what you compare it with. Compare home prices with local incomes and rents, and check how mortgage rates have changed what buyers can afford, rather than comparing Charlotte’s prices with other cities’ headlines.
Why is homeowners insurance going up in North Carolina?
Rates are set through a process involving the NC Rate Bureau and the NC Department of Insurance. A settlement announced on 17 January 2025 set an average statewide base-rate increase of 7.5% from 1 June 2025, well below the 42.2% the Rate Bureau had requested. Actual premiums vary by location, home and insurer; check the Department of Insurance for current rates.
How dependent is Charlotte on banking jobs?
Finance is one of Charlotte’s best-known industries. For the current number of financial-activities jobs in the metro, and how it compares with total employment, check the Bureau of Labor Statistics “Economy at a Glance” page for Charlotte-Concord-Gastonia. Any industry concentration means a downturn in that industry would be felt widely.
Is Charlotte’s population growth slowing?
Charlotte still added more people than any US city in 2024–25, but North Carolina’s growth slowed and international migration fell sharply, according to the state’s Office of State Budget and Management. It expects growth to slow later this decade. Check the latest Census and OSBM releases each year.
Sources
Checked 21 October 2026 at 9:54 PM ET.
- Freddie Mac, Primary Mortgage Market Survey: freddiemac.com
- NC Department of Insurance, “Commissioner Causey negotiates settlement on Rate Bureau’s homeowners’ insurance request” (17 January 2025): ncdoi.gov
- US Bureau of Labor Statistics, Charlotte-Concord-Gastonia Economy at a Glance: bls.gov
- NC Office of State Budget and Management, Demographic Outlook (7 April 2026): osbm.nc.gov
- US Census Bureau, Vintage 2025 city and town population estimates (released 14 May 2026): census.gov
- US Census Bureau, Building Permits Survey: census.gov
- City of Charlotte, Unified Development Ordinance (effective 1 June 2023): charlotteudo.org
Want to go deeper?
This article is part of our Charlotte Market series. The companion webinar, Why Charlotte: The Growth Math, covers both the growth story and the case against it, and how to test a deal against each risk.
Related reading:
- Start Here: A Plain-English Guide to Real Estate Investing in Charlotte
- Why Charlotte: The Growth Story and the Case Against It (coming soon)
- What Could Slow Charlotte Down (coming soon)
- Climate and Insurance Costs in the Carolinas (coming soon)
This article is for general education only. It isn’t legal, tax or investment advice, and it isn’t an offer to sell or a solicitation of an offer to buy any security. Any offering by Tide & Timber Investments is made only to persons with whom we have a pre-existing relationship, through formal offering documents. Real estate investing involves risk, including loss of principal. Rules, fees and market conditions change; confirm details with the relevant county, city or town and with your own financial, tax and legal advisers before you act.

